Dollar Shrugs Off Soft NFP Release
Weak September NFP
The US Dollar remains higher today despite Friday’s softer-than-forecast labour market report. The headline NFP release printed just 29k vs 89k expected, down sharply from the prior month’s 133k release which was itself revised lower from above 160k initially. The unemployment rate was also seen ticking back up to 4.2% from 4.1% prior and expected while wages growth was also softer at 0.1% from 0.3% prior and expected. In all, it was a weak report across the board though it had little impact on October hike expectations. The CME group was pricing in a roughly 25% chance of a hike before the data and a 19% chance now.
Diverging Central Bank Expectations
Still, despite these weakened near-term tightening expectations, USD remains well bid with traders still pricing in a hike for December. Part of the driver behind the current strength in USD is the weakness we’ve seen in EUR and JPY recently. The market has taken a less hawkish view on ECB and BOJ policy expectations which is dent the performance of those respective currencies. Looking ahead, USD looks poised to continue higher for now particularly while energy prices remain elevated and December tightening is still in focus. Only a shift in that narrative is likely to see any meaningful correction in USD near-term.
Technical Views
DXY
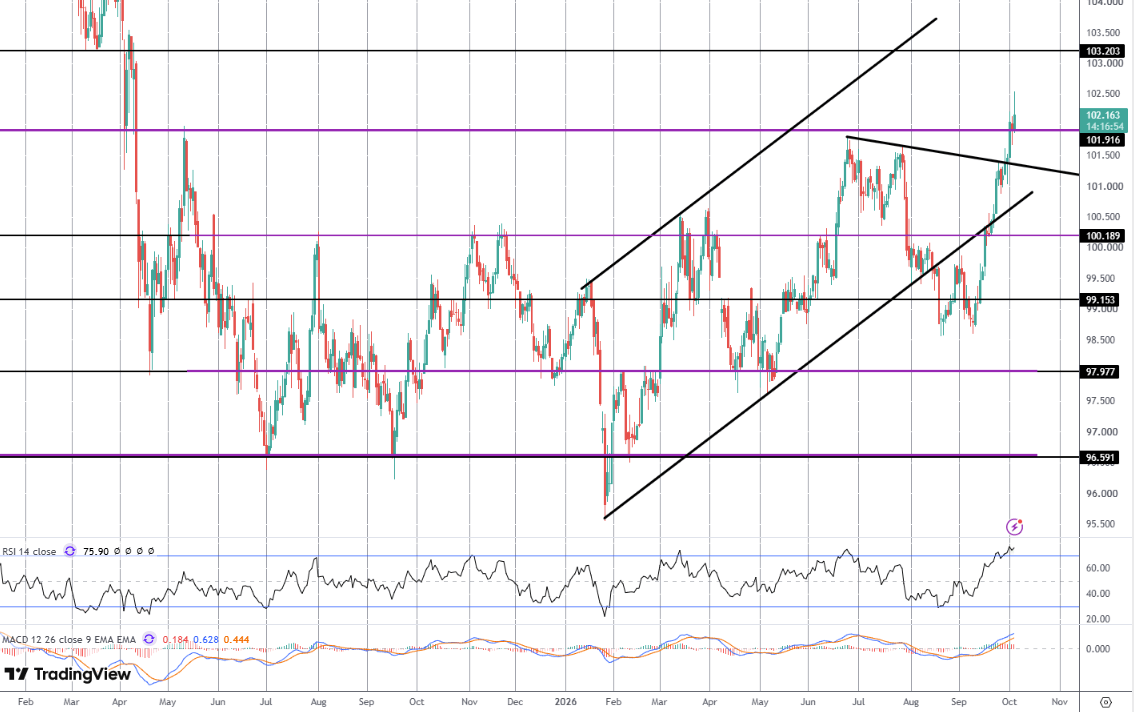
The rally has seen the index breaking out above the 101.91 level as the bull channel continues to develop. While above here and with momentum studies bullish, focus is on a continuation higher towards the 103.20 level next. The bull channel lows will be the key dynamic support to watch near-term as well as a retest of the broken bear trend line from summer highs.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 69% and 73% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
With 10 years of experience as a private trader and professional market analyst under his belt, James has carved out an impressive industry reputation. Able to both dissect and explain the key fundamental developments in the market, he communicates their importance and relevance in a succinct and straight forward manner.