FTSE Rallies GDP Growth Defies Forecasts
FTSE Rallies GDP Growth Defies Forecasts
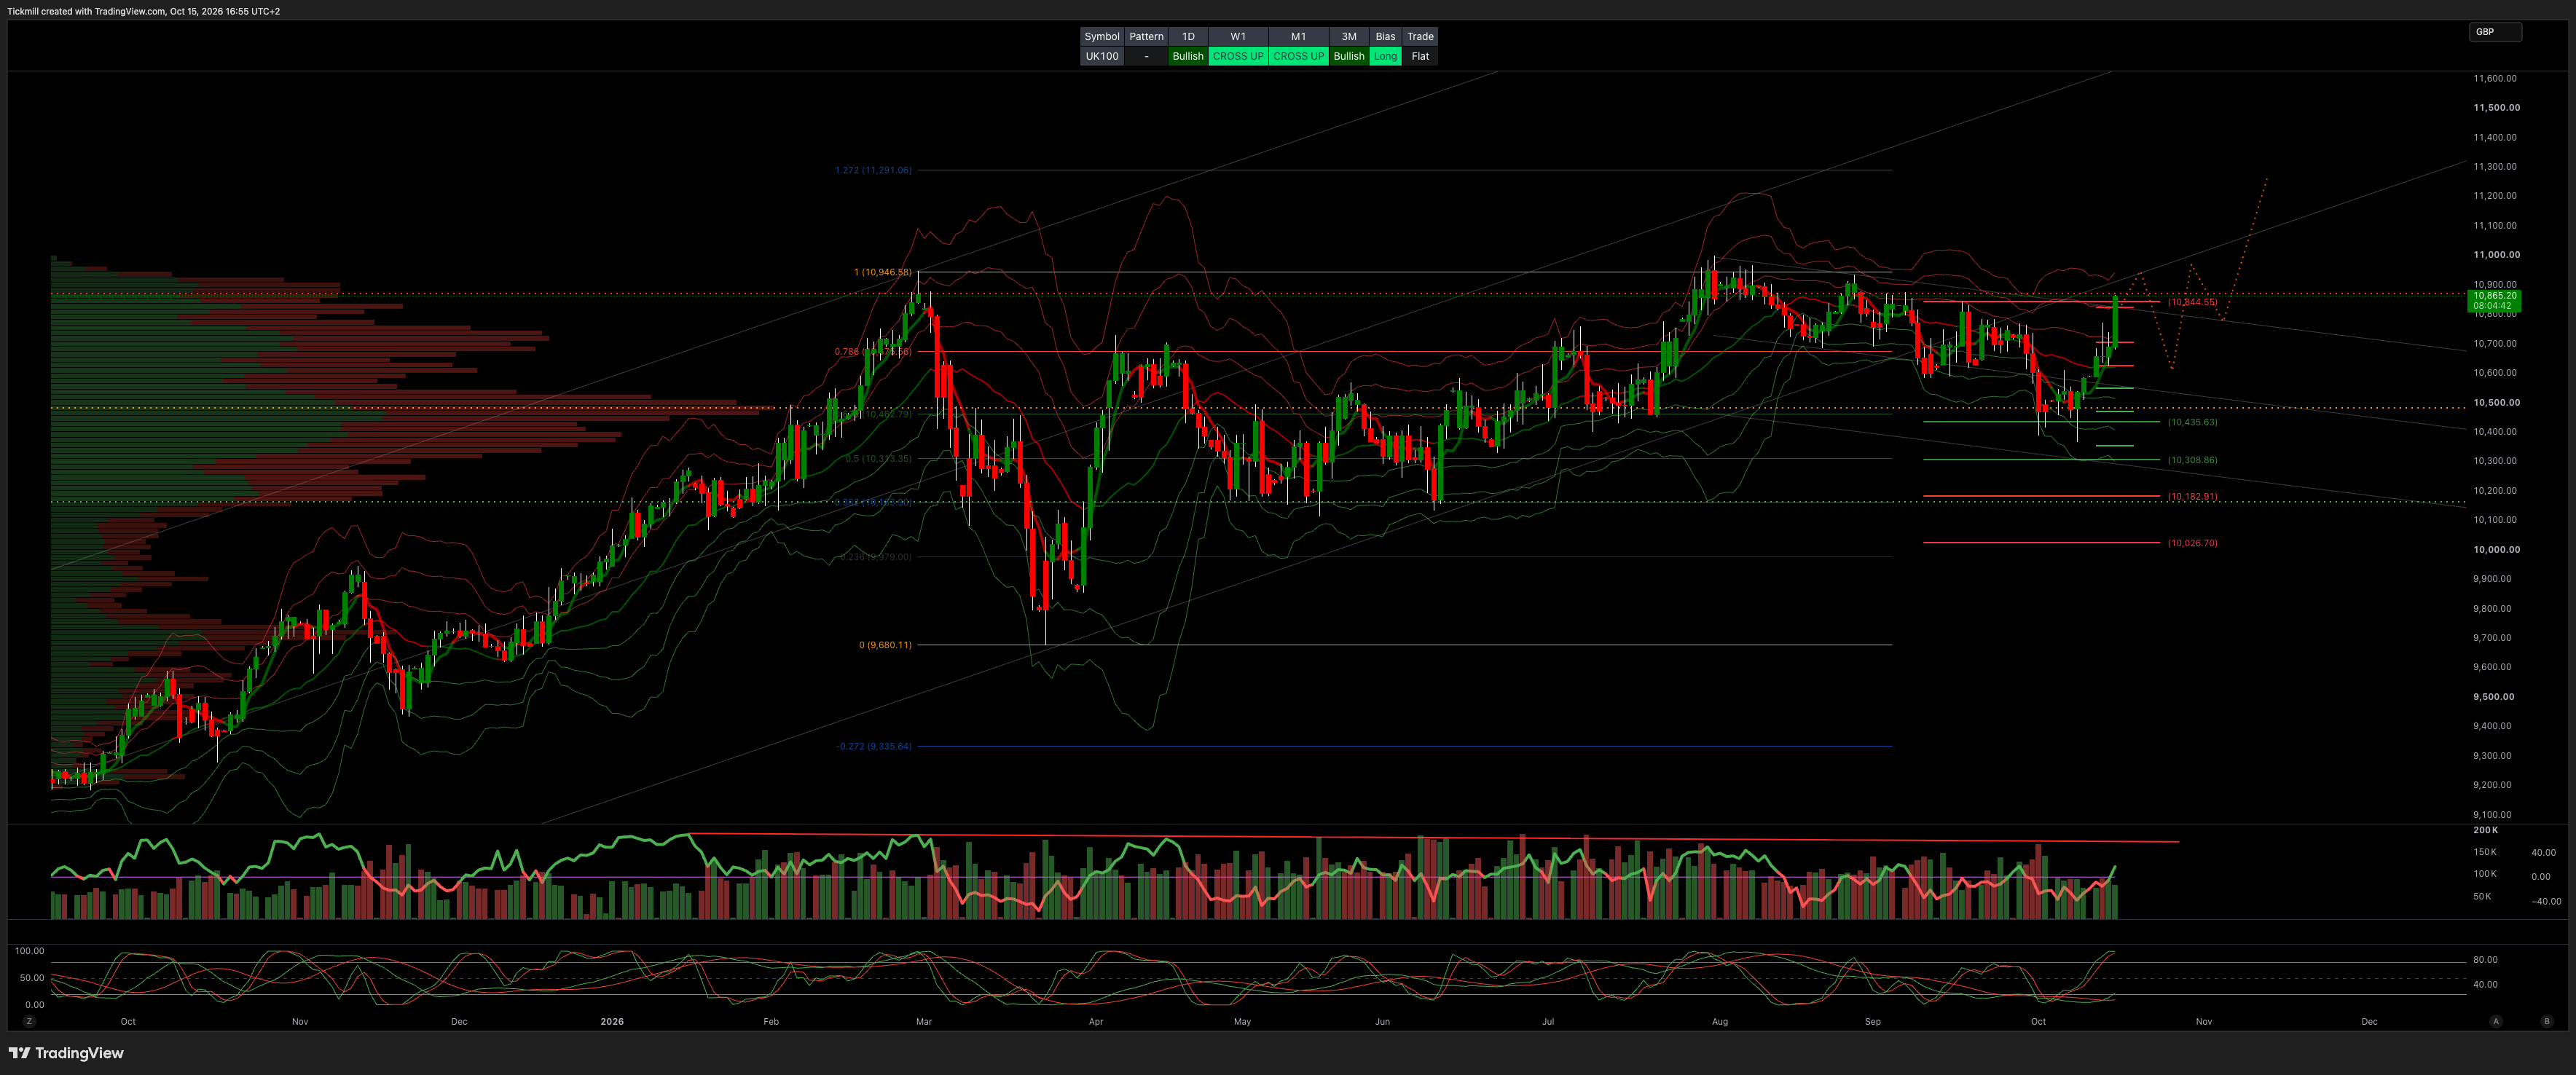
London's benchmark FTSE 100 rallied strongly on Thursday, powered by positive market sentiment following a better-than-expected domestic economic growth reading. The i The FTSE 100 closed around 10,850, adding 1.6% on the session and extending its trailing 12-month gains to over 15%. Broad-based market breadth saw only 24 out of the 100 constituent stocks finishing in negative territory.
Telecommunications, retail, and consumer heavyweights led the top-flight advance. BT Group surged over 4% to lead blue-chip gainers, while AutoTrader Group, British American Tobacco, JD Sports Fashion, and Compass Group all advanced more than 3%. Conversely, technology providers and select miners faced heavy selling pressure: IT services company Computacenter and miner Antofagasta led losses with declines exceeding 6%, while Polar Capital Technology Trust dropped over 5%.
On the domestic macroeconomic front, U.K. GDP expanded by 0.1% month-on-month in August, defying consensus expectations for a 0.1% contraction. Following a robust 0.4% expansion in July, the print puts the U.K. economy on track for a 0.7% quarter-on-quarter expansion in Q3—marking the eighth consecutive rolling three-month increase. Notably, this trajectory significantly outpaces the Bank of England's updated forecast of 0.4% Q/q. Sectoral data revealed industrial production rising 0.8% m/m (driven by a 1.2% jump in manufacturing output), while services output remained unchanged and construction dipped 0.2%.
In global markets, sentiment remained constrained by hotter-than-expected U.S. inflation data. Following Wednesday's elevated CPI figures, U.S. producer price inflation (PPI) spiked to 1.3% year-on-year in September versus 0.5% expected, while core PPI jumped to 0.7% m/m against 0.3% expected. Despite directionless Wall Street futures and mixed European benchmarks, the U.S. dollar retreated, with the Dollar Index losing 0.43% to 102.12. Sterling gained 0.40% to trade at $1.3245 (ranging between $1.3184 and $1.3276), while EUR/GBP edged to 0.8460 and GBP/JPY rose to 209.24. Aligning with a global softening in fixed income yields, U.K. 10-year Gilt yields dropped nearly 10 basis points to close at 5.3339%. Gold surged nearly 2%, crude oil traded directionless, and cryptocurrencies faced sharp downside pressure.
Finish Line: U.K. equities staged a firm rally as resilient August GDP data confirmed the economy's underlying momentum and helped push the benchmark back above the 10,800 mark. While persistent U.S. inflation readings and sharp pullbacks in tech and mining names provided friction, a retreat in sovereign Gilt yields and strong momentum across telecom and retail blue-chips kept the market on solid footing.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!